10 Notable Embedded Fintech Fundraises From August
August’s funding rounds show us how embedded finance is advancing on two fronts: AI-native systems are taking on more financial work inside accounting and industry-specific software, while payments, credit and insurance infrastructure is giving those platforms more ways to move money and manage risk. Those themes were also central to Great North Ventures’ September 2 […]
How Yardstik Is Moving Background Screening to Full Workforce Lifecycle Protection
The Minneapolis-based startup is using continuous monitoring, fraud detection and embedded screening to compete in a growing employment-screening market. Contractors and candidates typically undergo a background check before starting work. But the risks don’t end after that initial screening. Months later, a worker’s license could expire, they could commit an offense or could have been […]
How CapitalOS is building the financial layer for vertical software
CapitalOS enables software platforms to embed cards, bill pay, and wallets for their users and AI agents, while handling the complex infrastructure behind them, including underwriting, risk, compliance, and capital. By Ryan Weber For decades, business owners working as plumbers, electricians and other field-service technicians paid for expenses they incurred on the job with personal […]
What Stripe’s OpenRouter Deal Means for Embedded Finance
Embedded finance is moving deeper into business workflows and closer to the decisions made before a payment is made. On August 19, Stripe agreed to acquire OpenRouter for a reported $7.5 billion. The deal shows embedded finance is moving beyond payments and into the decision flows that generate them. OpenRouter is a three-year-old company whose […]
Building the infrastructure for modern loyalty
Benji CEO Nick Anastasiades in The Financial Revolutionist Loyalty has long been constrained by one-off integrations that are expensive to build, slow to launch and difficult to scale. As a result, many brands have been limited in how they can expand rewards ecosystems, while consumers are left with points and miles that often remain trapped […]
The Unconventional Path That Took a Small Midwest Startup to a Multi-Billion-Dollar Fintech Success
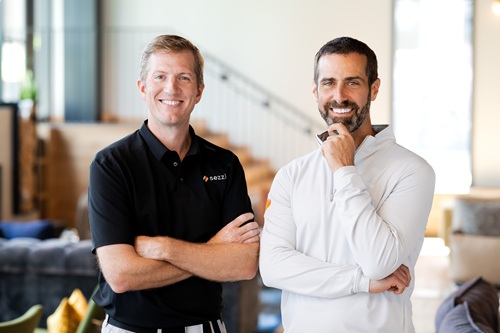
Its founders met at MBA school, faced some scary challenges over the years, but kept their eye on the consumer. Now valued at $3.5B+ on the Nasdaq, Sezzle isn’t done yet embedding value into its app and platform. by Graeme Thickens I first met cofounders Charlie Youakim and Paul Paradis in 2016, just months after […]
Why Loyalty is the Next Big Infrastructure Play (And Why We Doubled Down on Benji)
Why We Backed BenjiMost brands want loyalty partnerships. Almost none have the infrastructure to launch them fast. Loyalty is one of the fastest-growing parts of the consumer economy, yet it still runs on custom deals and manual integrations, with engineering timelines that can stretch a year or more. Benji is building the modern tooling that […]
The New York Times highlights Waterlily’s approach to long-term care

Long-term care costs upwards of $80,000 a year at home and $130,000 for a nursing home bed, yet only 15% of Americans over 65 have any insurance to cover it. Government has no comprehensive answer for it, making it one of the largest uninsured risks in American life. Our portfolio company Waterlily uses AI and […]
Branch + Stripe: Why this partnership is a signal, not just a story
One of our portfolio companies made news last week, and the announcement is significant: it represents exactly the kind of embedded finance milestone we look for when we back a company. On March 25, Branch, a provider of workforce financial infrastructure, announced it has become the embedded digital wallet provider for worker payouts within Stripe […]
Fintech for good: How embedded APIs and AI can drive economic mobility
Financial services are moving upstream into the platforms where income is generated. Tens of millions of Americans face a major hurdle in achieving financial self-sufficiency. These individuals can’t be easily underwritten by traditional risk scoring systems. This means they can’t rent an apartment, qualify for a small business loan, or build credit history. According to […]